
Thousands miss out as SFI budget disappears within hours
Our benchmark spot prices (East Midlands)
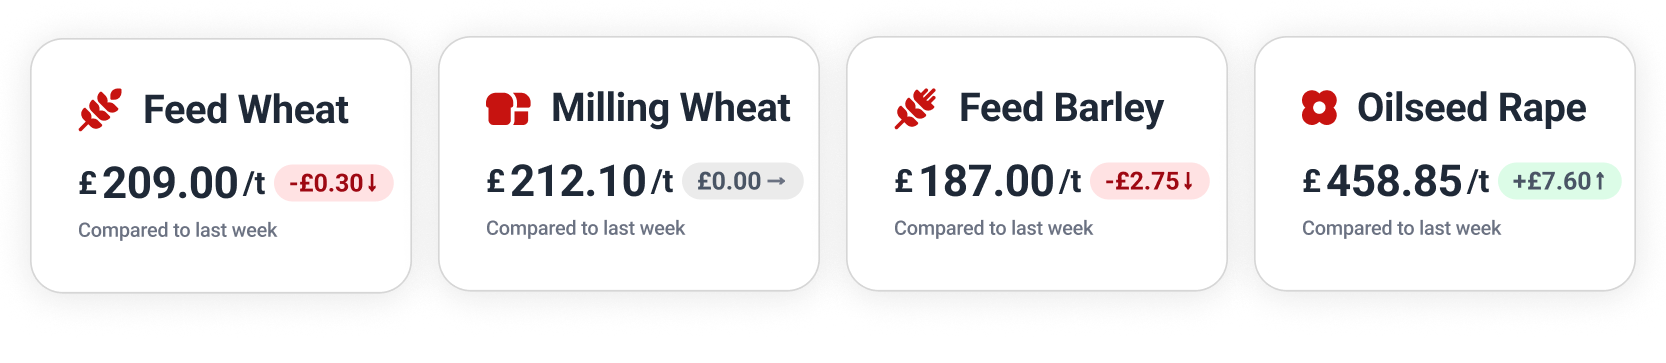
Feed Wheat
The UK SFI budget was exhausted in under six hours on Tuesday, as the second application window faced intense demand. Thousands of farm businesses were left empty-handed until 2027.
Meanwhile, AHDB’s September balance sheet estimated a total UK wheat supply, including opening stocks and imports, of 16.55 million tonnes for the 2025/26 season. This is nearly 800,000 tonnes higher than recorded end destinations for the grain, a much higher than average residual – suggesting we need to be cautious about the precision of current supply and demand figures.
With high nitrogen prices affecting prospects for winter wheat, some farmers are looking at hybrid rye as a high-yielding, lower-cost alternative, as it requires less nitrogen and provides high-protein grain for pig feed.
After a weak end to last week, November 2026 London feed wheat started strongly, hitting £211.25 at Monday’s close. The contract then lost momentum, slipping back to £208.25 on Wednesday, and to £207.50 by Thursday’s end.
For full spot and futures market analysis, check our Insights on Hectare Trading.
Milling Wheat
The International Grains Council estimated that global wheat flour trade in 2025/26 dropped to 15.1 million tonnes (in the equivalent wheat volume) – a five-year low.
Meanwhile, Coceral forecast a total EU durum wheat production in 2026 of 7.57 million tonnes, down from 8.54 million tonnes in 2025.
In South East Asia, milling wheat supplies are increasingly disrupted by Black Sea export bottlenecks. Importers in Indonesia and Vietnam are now paying premiums for replacement cargoes of Australian and US wheat.
Paris milling wheat futures have failed to hold on to their early-September highs. The December 2026 contract climbed to €243.75 (£209.09) on Monday, but eased back to €240.50 (£206.71) by Wednesday’s close, then to €237.50 (£204.32) on Thursday.
Feed Barley
As the UK malting barley market remains weak due to soft demand from the whisky and distilling sectors, more malting barley is finding its way into feed channels, creating a temporary surplus of feed barley. With a variable 2026 harvest quality, maltsters are enforcing strict selectivity, increasing malting barley downgrades.
Frustration over disappointing 2026 yields, high nitrogen fertiliser costs and narrow malting premiums is causing some UK growers to reassess winter barley acreage for next season.
Oilseeds
Dry conditions in France and severe flea beetle pressure across the UK are compromising establishment of the 2027 oilseed rape crop.
Meanwhile in Australia, analysts have raised the canola crop forecast to 7.86 million tonnes, with record export projections of 6.75 million tonnes. Chinese crushers recently bought new-crop Australian canola, marking the first private Chinese purchases of Australian seed since 2020 restrictions were lifted. Australia expects to ship 2.2 million tonnes of canola to China, competing directly with Canadian supplies.
Paris rapeseed futures have generally maintained their late-August gains so far this month, while trading in a narrow range. The November 2026 contract jumped to €556.25 (£477.15) on Monday, dropped to €552.00 (£473.51) on Tuesday, then recovered to €554.00 (£476.16) on Wednesday, before tailing off to €549.50 (£472.77) on Thursday.
Wanted Crop
🌾 Group 3 or 4 soft wheat (10.2/74/130) required for collection in the South East, East Midlands and East of England. Movement in September 2026, with a guide price of £200–210/t ex-farm.
🌾 Feed wheat is wanted for collection in Yorkshire and the Humber and the East of England, for movement this month. Guide price of £208/t ex-farm.
🌾 Group 1, 2 or 4 hard wheat required for collection in the East Midlands and Yorkshire and the Humber. Movement in September 2026, with a guide price of £210–214/t ex-farm.
This article is for general information only and does not constitute advice. While we make every effort to ensure the accuracy of the content at the time of publication, Hectare Trading makes no guarantee regarding the data provided.