
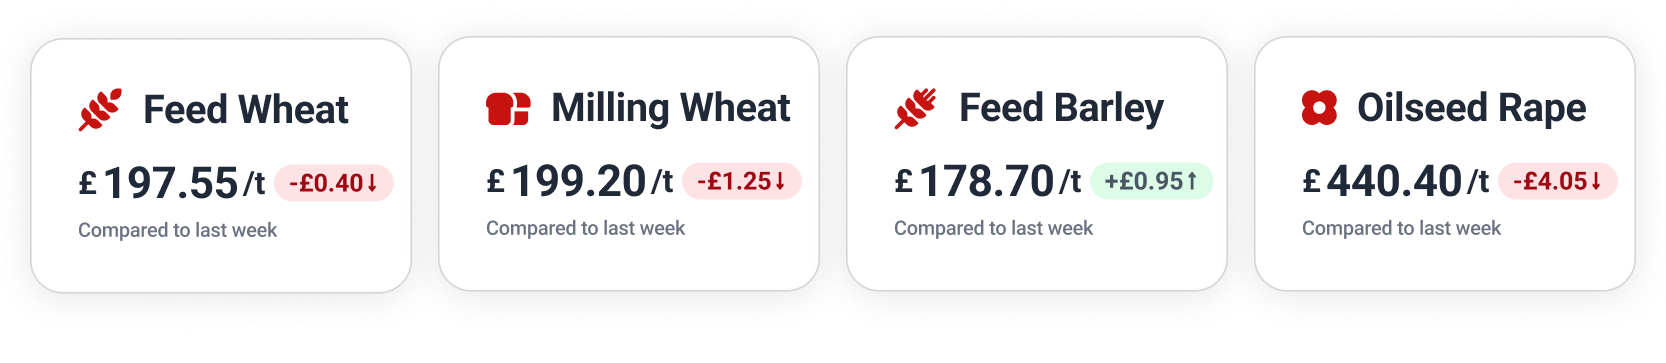
Our benchmark spot prices (East Midlands)
Feed Wheat
After expanding Southern Hemisphere supply forecasts, Chicago wheat futures finished October with a ninth consecutive weekly decline, placing downward pressure on European wheat futures.
Meanwhile, weather challenges in Eastern Europe have increased the proportion of feed wheat on the global market. For instance, the milling-quality share of Romania’s 13.5 million tonne wheat harvest fell from 85% last year to 55%, creating a much larger pool of competing feed wheat.
October ended with the November 2026 London feed wheat contract at £192.75 and the May 2027 contract at £202.50. This week both markets eased back, the November contract closing Wednesday at £190.50. The May contract dropped below £200 on Thursday at £199.50, the November contract finishing at £189.75.
For full spot and futures market analysis, check our Insights on Hectare Trading.
Milling Wheat
High domestic wheat prices in Turkey are reducing profit margins for flour millers. Turkey’s leading position in global flour exports faces increasing competition as key African import destinations build out their own domestic flour mills.
US third-quarter flour production dropped 1.3% year-on-year to around 4.76 million tonnes, the lowest volume in 20 years. Semolina production from durum wheat fell 6%, leaving US milling capacity utilisation at a subdued 83.6%.
Paris milling wheat futures have struggled for momentum this week. The December 2026 contract inched forward to €228.25 (£190.77) on Monday, then fell away to €224.00 (£186.95) by Wednesday’s close, and further to €223.00 (£185.97) on Thursday.
Feed Barley
High fertiliser costs have pushed Australian farmers to shift acreage from wheat to barley, requiring significantly less nitrogen. Australia’s barley crop is forecast to hit a record 17.7 million tonnes with exports reaching 13 million tonnes, generating heavy competition in global feed grain markets.
Ukrainian barley exports dropped more than sixfold year-on-year in October to just 34,000 tonnes amid ongoing port infrastructure challenges, while Turkey’s record grain harvest has slashed its barley import requirements to just 150,000 tonnes.
Oilseeds
Canada and China agreed to extend their agricultural trade deal through to the end of 2028, securing market access for Canadian canola seed and meal. Canadian canola seed exports to China have surged 84% to $1.91 billion since Chinese tariffs were lifted.
Australia is also looking to renew canola exports to China, after six years of trade restrictions. Chinese inspectors recently completed a formal audit of Australia’s canola production and supply chains, a precursor to resuming imports.
After finishing October at €557.00 (£464.71), the May 2027 Paris rapeseed contract pulled back sharply to €549.00 (£458.03) on Monday, as crude oil prices started to slide. Weakness continued throughout the next three days, the contract sinking to €532.25 (£444.06) on Wednesday and €528.75 (£441.14) on Thursday.
Wanted Crop
🌾 Group 3 or 4 soft wheat (10.2/74/130) is wanted for collection in the East of England, for movement in May 2027. Guide price of £198–202/t ex-farm.
🥣 Oats required for collection in the South West. Movement between November 2026 and January 2027 with a guide price of £170/t ex-farm.
🌾 Feed barley is wanted for collection in the West Midlands and East Wales. Moving this month with a guide price of £180–190/t ex-farm.
🌾 Group 1 wheat required for collection in the South East and East of England, for movement in December. Guide price of £190.50–202.50/t ex-farm.
🌾 Group 4 hard wheat (10.2/74/130) is wanted for November collection in the East of England, with a guide price of £192–197/t ex-farm.
This article is for general information only and does not constitute advice. While we make every effort to ensure the accuracy of the content at the time of publication, Hectare Trading makes no guarantee regarding the data provided.