
Our benchmark spot prices (East Midlands)
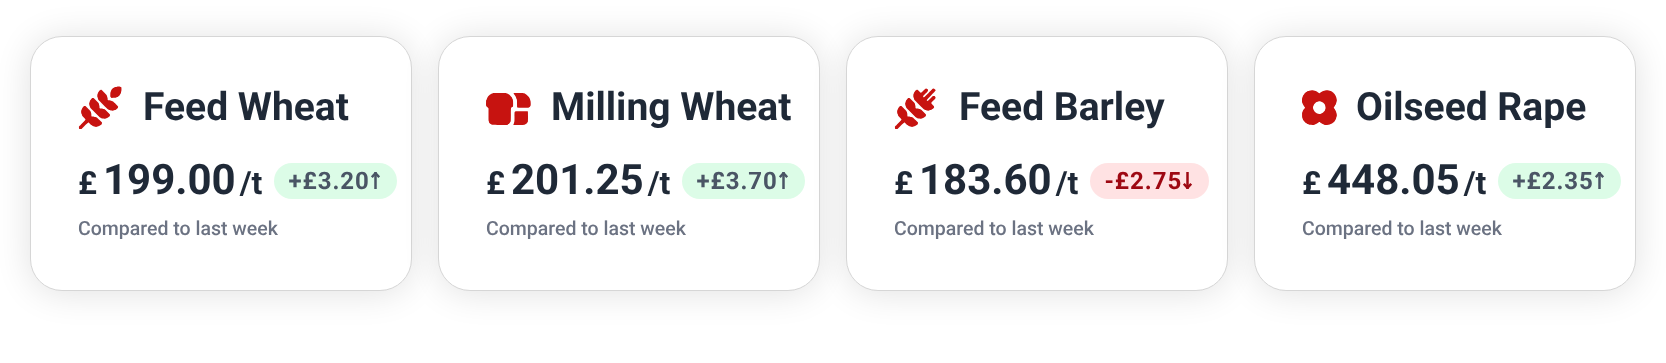
Feed Wheat
Despite Chicago wheat snapping its 10-week run of lower weekly closes, UK and European wheat markets remain relatively firmer than their US counterparts due to tight near-term availability.
Longer-term supply concerns were also raised as the AHDB Early Bird Survey indicated that the UK wheat area for harvest 2027 will rise by just 1% to 1.664 million hectares.
The actual figure could, however, by higher as ideal autumn weather has allowed rapid drilling behind early sugar beet harvests, and significant acreage initially destined for spring barley or failing oilseed rape (damaged by cabbage stem flea beetle) has been patched or drilled with winter wheat instead.
As the November 2026 London feed wheat contract winds down, attention turns to May 2027 prices. After finishing last week at £203.75, the May 2027 contract started with two days of modest gains, closing Tuesday at £206.00. Following a £3 dip on Wednesday, the contract rebounded to end Thursday at £205.50.
For full spot and futures market analysis, check our Insights on Hectare Trading.
Milling Wheat
In France, soft wheat planting has progressed smoothly, reaching 90% complete, well ahead of the 82% five-year average for this stage of the year. French soft wheat exports outside the EU are now expected to reach 7.2 million tonnes in 2026/27 due to continued Black Sea supply disruptions.
Correspondingly, Southeast Asian buyers have booked 1.1 million tonnes of Australian wheat to move in October and November, pushing average Australian port prices to two-year highs.
Brazil’s flour milling industry must import an estimated 8.94 million tonnes of milling wheat (primarily from Argentina) to cover domestic requirements, following El Niño-driven downpours that have cut Brazil’s projected wheat crop by a third and damaged milling quality.
Paris milling wheat futures struggled to hold gains this week. The December 2026 contract rose to €235.25 (£196.32) on Monday and €235.75 (£196.39) on Tuesday, but sank back to €233.00 (£194.07) on Wednesday. Another rally brought the contract back up to €237.25 (£198.75) by Thursday’s close.
Feed Barley
The AHDB survey projected an 11% drop in the UK spring barley area for harvest 2027 to 531,000 hectares – the smallest planted area since 2006 – as growers react to consecutive challenging dry spring seasons that caused poor yields, high input costs and financial losses.
The winter barley area is also pegged down 1% to 366,000 hectares, bringing the total UK barley area down 7% to 897,000 hectares.
Meanwhile, Australia achieved a record 11.48 million tonnes of barley exports in 2025/26, up 25.3% on the previous record set in 2017, comprising 9.04 million tonnes of feed barley. China took over 80% of total shipments and accounted for 96% of Australia’s September feed barley exports.
Oilseeds
Russian drone and missile strikes intensified against Ukrainian agricultural targets, prompting major agribusinesses to halt operations at oil extraction plants and suspend seed purchases.
In the US, soybean crushing hit an all-time monthly record of 234.2 million bushels. Forecasts indicate that the US biofuel sector is set to surpass the food sector in domestic soybean oil consumption for the first time in 2026/27.
USDA projects that global rapeseed oil output will rise to 38.2 million tonnes in 2026/27, with the EU leading production at 10.8 million tonnes. Total global rapeseed production for 2026/27 was revised up by 680,000 tonnes to a record 100.3 million tonnes.
Paris rapeseed futures have been on a journey this month, the February 2027 contract dropping to a three-month low of €522.75 (£436.05) on 6 November before climbing to €543.50 (£452.76) by this Tuesday’s close. After a sharp pullback to €532.75 (£443.73) on Wednesday, the contract responded well to finish Thursday at €540.00 (£452.40).
Wanted Crop
🌾 Feed barley is wanted for collection in the West Midlands. Moving this month with a guide price of £185–188/t ex-farm.
🌾 Feed wheat is wanted for collection in the North East for March 2027 movement. Guide price of £205/t ex-farm.
🌾 Group 3 or 4 soft wheat (maximum protein 12.5%) required for collection in the South East, East Midlands and East of England. Moving between November and January with a guide price of £195–205/t ex-farm.
🌾 Rye is wanted for December collection in Yorkshire and the Humber. Guide price of £160–170/t ex-farm.
This article is for general information only and does not constitute advice. While we make every effort to ensure the accuracy of the content at the time of publication, Hectare Trading makes no guarantee regarding the data provided.