
Our benchmark spot prices (East Midlands)
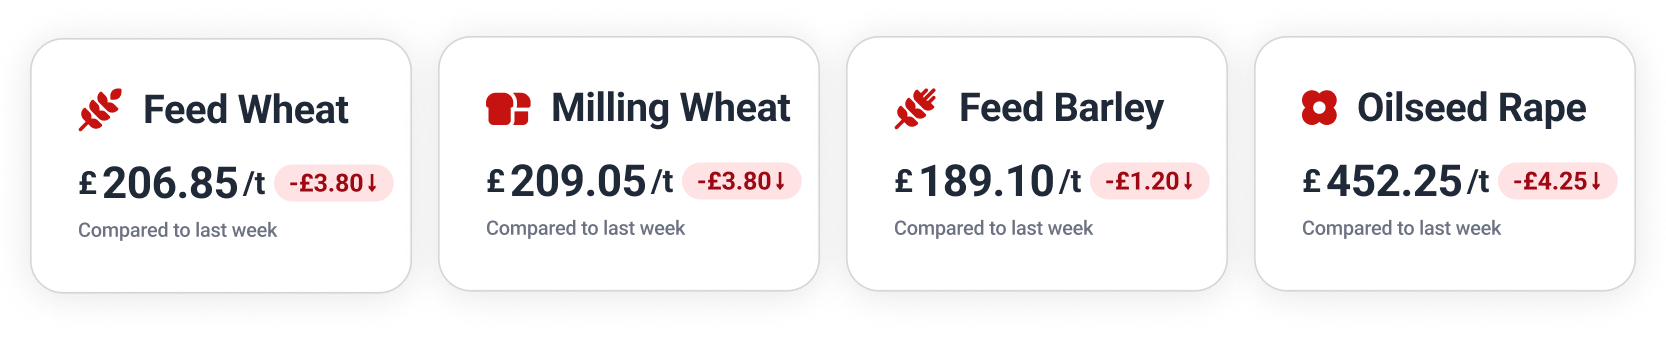
Feed Wheat
Global wheat markets were swept up by the US corn collapse after last Friday’s WASDE report predicted an unexpected rise in US corn production for 2026/27, by 234 million bushels to 16 billion bushels.
Meanwhile, the USDA cut its forecast for European wheat ending stocks for June 2027 to 11.7 million tonnes – a 38% drop from this year’s estimate of 19 million tonnes – due to raised domestic EU consumption.
Caught between these structural factors, London feed wheat futures have been relatively flat this week. After inching forward to £206.25 on Monday, the November 2026 contract gained another 50p over Tuesday and Wednesday to close at £206.75. On Thursday the contract slid back to £205.50.
For full spot and futures market analysis, check our Insights on Hectare Trading.
Milling Wheat
In Australia, the price spread between Australian Premium White and Australian Standard White wheat widened to $24/t, hitting its highest level since July 2023 due to a shortage of high-protein grain.
Canadian Western Red Spring wheat has maintained high quality despite harvest rains, with 77% meeting the top two grades at an average protein content of 14%. This positions Canada well to supply milling markets amid Black Sea shipping disruptions.
Paris milling wheat futures have been more active this week than London, the December 2026 contract climbing €3.75 over Monday and Tuesday to finish at €245.75 (£207.56). After climbing further to €248.25 (£209.49) on Wednesday, the contract eased off to €246.25 (£208.08) by Thursday’s close.
Feed Barley
Defra confirmed that England’s 2026 combined cereal and oilseed harvest dropped to 16.03 million tonnes – the lowest level since statistical records began in 1984 – following spring and summer heatwaves and drought.
English barley production was especially disappointing, falling 11% to 3.7 million tonnes, the smallest crop since 2012. Spring barley production collapsed 23% to 1.7 million tonnes, on a 17% drop in planted area and an 8% fall in average yields.
Oilseeds
In Canada, as the Prairie harvest nears completion, canola selling has surged – recording its second-highest weekly delivery total in over 25 years.
Australia’s canola output is forecast to reach a record high of 8.1 million tonnes in 2026/27, providing a strong offset to an 8% drop in overall winter grain output.
China is anticipating an uptick in rapeseed imports this quarter to replenish depleted domestic inventories, which is expected to limit upside potential for domestic rapeseed oil prices.
After dropping dramatically to €502.00 (£425.51) last week, the November 2026 Paris rapeseed contract recovered early this week. A €15 jump on Monday took the contract to €517.00 (£436.75), followed by further gains to €522.00 (£440.49) at Wednesday’s close. Another collapse, however, on Thursday brought the contract back to €499.75 (£422.32).
Wanted Crop
🌾 Group 1 wheat is wanted for collection in Yorkshire and the Humber and the East Midlands, moving this month. Guide price of £212–215/t ex-farm.
🌾 Group 1, 2 or 4 hard wheat required for collection in Yorkshire and the Humber. Movement this month with a guide price of £208–212/t ex-farm.
This article is for general information only and does not constitute advice. While we make every effort to ensure the accuracy of the content at the time of publication, Hectare Trading makes no guarantee regarding the data provided.