
Our benchmark spot prices (East Midlands)
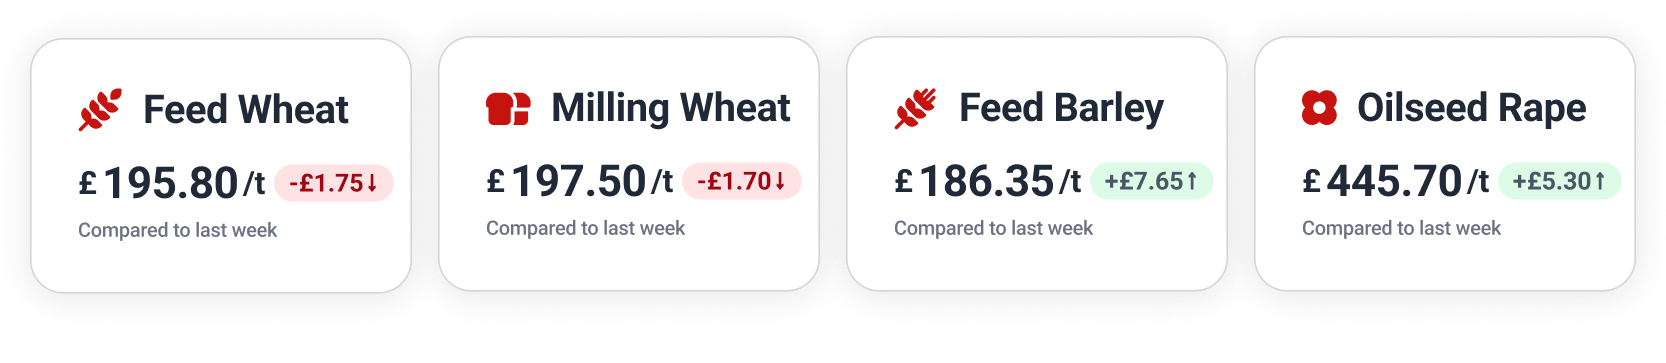
Feed Wheat
The November WASDE report surprisingly raised projected 2026/27 global wheat ending stocks by 4.78 million tonnes to 280.82 million tonnes, driven by higher production forecasts for Australia, Argentina, Kazakhstan and Ukraine.
Any downward pressure on European wheat markets was however outweighed by the collapse of the Abu Dhabi peace talks without a Black Sea shipping agreement, as commercial shipping in the Black Sea was shown to have dropped 37% year-on-year in October.
After giving up ground last week, London feed wheat futures staged a minor recovery. The November 2026 contract regained £190.00 on Monday, then climbed to £194.75 by Wednesday’s close, while the May 2027 contract finished Wednesday at £204.50. In more subdued trading, both contracts lost £1.75 on Thursday, November ending at £193.00, May ending at £202.75.
For full spot and futures market analysis, check our Insights on Hectare Trading.
Milling Wheat
The high volume of quality wheat in the UK has sharply reduced domestic demand for imported bread-making wheat, while continuing to squeeze milling premiums for growers, offering little compensation for drought-reduced yields.
AHDB recently confirmed that 79% of UK Group 1 wheat met standard milling specifications, surpassing the previous 2003 record of 52%, with an all-time high average protein content of 13.8%.
Supply concerns have meanwhile emerged in Brazil, where heavy rain has cut domestic wheat production forecasts to under 6 million tonnes, while a significant portion of Argentina’s crop has failed to meet the baking standards required by Brazilian millers.
The December 2026 Paris milling wheat contract rose to €226.75 (£189.18) on Monday. Gains then accelerated as the contract ended Wednesday €9.50 higher at €236.25 (£197.55). The market paused on Thursday, the December contract retreating to €232.50 (£194.20) by the close.
Feed Barley
Australia’s 2026/27 barley production is forecast to reach a record 17.7 million tonnes (up 4.4% year-on-year and 40% above the 10-year average), driven by Southern growers shifting away from high-fertiliser crops like wheat and canola. Exports are projected at a record 13 million tonnes, rising from last year’s all-time high of 11.48 million tonnes.
This provided a major contribution to WASDE’s global barley production forecast of 161.1 million tonnes, 1.0 million tonnes higher than October’s report.
By contrast, Ukrainian farmers are drastically cutting winter barley plantings, due to negative margins and logistics bottlenecks. Total winter barley area for the 2027 harvest is projected to barely exceed 500,000 hectares.
Oilseeds
United Oilseeds reported that UK farmers drilled 387,000 hectares of oilseed rape for the 2027 harvest, up more than a third year-on-year. Conversely, the European Commission forecast that total EU oilseed production would fall by 1.1% to 31.11 million tonnes in 2026/27, partly due to weaker rapeseed prospects in Poland.
Canada’s domestic canola crushing capacity has expanded from roughly 11 million to 15 million tonnes annually following heavy processing investments, creating fierce competition with exporters for domestic seed against a slightly smaller 2026 crop of 22.1 million tonnes.
Between the end of October and the end of last week, the February 2027 Paris rapeseed contract sank €32.50 to €522.75 (£436.05). This week has seen something of a recovery, the contract regaining €540.00 (£451.54) on Wednesday. The rally slowed down on Thursday, the February contract closing slightly up at €540.50 (£451.47).
Wanted Crop
🌾 Feed barley is wanted for November collection in North Eastern Scotland. Guide price of £152–155/t ex-farm.
🌾 Group 1 wheat is wanted for collection in Yorkshire or the East Midlands. Moving this month with a guide price of £197–205/t ex-farm.
🌾 Group 1, 2 or 4 hard wheat (10.2/74/130) required for collection in the East Midlands and East of England, for November movement. Guide price of £190–195/t ex-farm.
🌾 Group 1 wheat is wanted for collection in the East Midlands and East of England. Moving in December with a guide price of £195–200/t ex-farm.
This article is for general information only and does not constitute advice. While we make every effort to ensure the accuracy of the content at the time of publication, Hectare Trading makes no guarantee regarding the data provided.